



How to Start a FinTech Company in 2026: A Step-by-Step Guide
Last updated:20 October 2026
Global FinTech investment hit $103.1 billion in the first half of 2026, up from $72.2 billion in the second half of 2025, according to KPMG's Pulse of FinTech. The ten biggest deals made up 62% of that total, and the deal count fell to 2,100. Capital is concentrating in fewer, larger companies.
A new founder walks into that market, and anyone learning how to start a FinTech company has to understand it first. If you want to start a FinTech company today, you are not entering a quiet field. You compete with funded players, with traditional banks that now ship their own apps as part of digital transformation programs, and with regulators who watch new companies closely.
We have spent years building FinTech products for founders and financial institutions, and the same questions come up in almost every first call. Which license do I need? Can I launch on someone else's bank charter? What does it cost, and how long until we can take a real payment?
In our new article, we cover how to start a FinTech company from the first idea to a regulated launch: choosing a niche, picking a bank or BaaS partner, handling compliance, budgeting, building the MVP, and funding the whole thing.
Key takeaways
- Starting a FinTech company is mostly a regulatory and partnership decision, and only after that a software project.
- You can launch in three ways: partner with a bank, build on a Banking-as-a-Service (BaaS) provider, or apply for your own license. Most early-stage FinTech startup teams start with the first two.
- Budget from about $100,000 for a narrow MVP to several million dollars for a regulated product that holds customer funds.
- Sponsor-bank oversight tightened after the 2024 Synapse collapse. Your bank partner will ask hard questions about your compliance program before you ever go live.
- Most FinTech startups fail on distribution, unit economics, or compliance, rarely on the code.
What Does It Take to Start a FinTech Company?
A FinTech company uses software to deliver or improve financial products: payments, lending, investing, insurance, accounting, or banking across the wider financial sector. The term is short for financial technology, and the FinTech sector now covers everything from a two-person remittance app to a company processing billions in card volume.
The path to start a FinTech company has seven steps, and they overlap more than most guides admit. Pick a niche and validate it, decide how you will operate legally, and map the regulations that apply. Then cost the launch, build a lean MVP with the right team, secure funding, and win your first customers without burning the budget.
Founders type "how to start FinTech company" into a search bar expecting a checklist, but the real answer starts with the operating model. Writing code only comes in step five.
Founders who start with the app often learn six months later that their chosen model needs a license they cannot get, or a bank partner who will not sign. We have watched teams hit this wall, and it is expensive to fix.
Learn about our expertise in the industry and what we have to offer


How Do You Pick a FinTech Niche and Validate the Idea?
Working out how to create a FinTech startup?
Start with a specific financial problem for a specific group of people, one that helps them reach their financial goals. "Payments for everyone" is not a niche; "Cross-border payouts for freelancers in Latin America" is.
Every FinTech startup that gains traction begins with a narrow target audience. A tight target market lets you understand its pain, price accurately, and reach customers without a large marketing budget.
Validate demand before you build
Before you write a line of code, do the market research that predicts market demand. Interview 30 to 50 potential customers, and ask what they do today instead of your product, what it costs them, and what they have already tried.
Check search demand in Google Trends. Read the one- and two-star reviews of the top apps in your niche, because that is where unmet needs are written out for you.
Common FinTech niches
Here are the niches we see founders pick most often, and what each one asks of you:
FinTech startup ideas with less competition
If you want ideas that are less saturated, look at the edges: tools for small-business payables, finance for gig workers, cross-border B2B payments, or compliance software sold to other FinTech businesses. Remittance companies and other payment firms carry the heaviest licensing load, while personal finance tools carry the lightest. A saturated market is not a closed one, but you need a competitive advantage that gives a customer a reason to switch.
Should You Partner With a Bank, Use a BaaS Provider, or Get a License?
No other decision in this article shapes your business model, business structure, cost, and timeline as much as this one. You have three routes.
For most first-time FinTech startup founders the answer is a bank partnership or a BaaS provider. Your own license makes sense once you have proof that customers want the product and the transaction volumes to justify the cost of compliance.
Can you start a FinTech bank?
People search "how to start a FinTech bank" all the time, and the answer depends on what you mean. Becoming a chartered bank takes significant capital and years of regulatory work.
Most founders mean something else: a digital banking product, such as accounts, cards, and transfers, sold under their own brand. You can build that on a partner bank's charter without becoming a bank yourself.
What the Synapse failure taught the industry
In 2024, the BaaS middleware company Synapse collapsed, and thousands of Americans found their deposits frozen. The damage was not a technology bug. Nobody could say with certainty who held which balance, because the records sat across several parties.
Regulators responded by looking harder at sponsor banks and the FinTechs they support. In practice, expect a detailed due diligence process.
Expect to prove you can reconcile every customer balance daily, and expect contract clauses that say what happens to customer funds if you, or the bank, fail. Choose a partner who has clean answers to those questions, and ask for them in writing.

Which Regulations Apply to a FinTech Startup?
The rules depend on your product and your market, and the regulatory requirements for a payments app differ from those for a lending platform. Some obligations show up almost everywhere, and you should plan for them from the first sprint. You also need to meet the legal standards of every market you serve.
AML and KYC
Anti-money-laundering programs and know-your-customer checks are the baseline for almost any product that moves or holds money. You will need identity verification at onboarding, transaction monitoring, and a process for reporting suspicious activity. Buying the identity layer is usually faster than building it, so choose KYC compliance software before you design onboarding.
PCI DSS
If you store, process, or transmit card data, you fall under the Payment Card Industry Data Security Standard. The current version is v4.0.1, and its future-dated requirements became mandatory on 31 March 2025, so new projects should build to it from the start and plan for the 12 PCI DSS requirements early. Using a certified payment processor can shrink your scope.
GDPR
If you handle personal data of people in the European Union, the General Data Protection Regulation applies to you, wherever your company is based. It affects how you collect consent, store financial data, and handle deletion requests.
Licensing
Payment licenses, lending licenses, and investment registrations are common requirements. You can obtain licenses yourself or work with a partner who holds them.
Some regulators, including the UK's Financial Conduct Authority, run regulatory sandboxes that let you test a product with real customers under supervision before a full application. If you plan to enter global markets, map each country's rules separately.
How Much Does It Cost to Start a FinTech Company?
The question we hear most often is "how much does it cost to start a FinTech company?" The range is wide: from about $100,000 for a narrow MVP to several million dollars for a regulated product that holds customer funds and runs its own compliance function.
What drives the cost
The spread comes from five cost drivers, and the first two do most of the damage.
Build a team to realize your idea
You must know WHAT you want to achieve with their innovative financial products or services. However, you often require guidance on the crucial HOW. This is where a trusted technology partner comes into play, a collaborator dedicated to the success of the fintech startup.
Such technology partners offer invaluable advice across various dimensions, including infrastructure, tools, and solution architecture. Their support enables cost optimization, facilitates the development of new features, and aids in selecting the technology stack that expedites the realization of business objectives far more efficiently than attempting to navigate these intricacies independently.
Development companies have preferences regarding tech stacks, encompassing programming languages, frameworks, and databases used for website and app creation. Hence, it's crucial to engage a development team well-versed in crafting FinTech applications.
One viable option is building your team through a partnership with a reputable fintech software development company like TechMagic. Prioritize competence and experience, evaluate tech stack expertise, and explore nearshore options when deciding.
As Steve Jobs wisely noted, "Great things in business are never done by one person. They are done by a team of people." Attracting and recruiting top talent for your startup can be a daunting task, especially in the technology sector.
What founders forget to budget for
Do not budget for the build alone. A common mistake is to fund the MVP and discover that compliance, security testing, and the first year of marketing need as much again.
Run the numbers on time to market as well, since every month of delay adds payroll and legal cost. Plan for at least 12 months of runway after launch, because regulated products rarely hit break-even in the first year.
If a FinTech app is your main product, how to create a FinTech app breaks down development cost by feature and platform. Here we stay on the company around the product.
How Do You Build the MVP and the Team?
When you plan how to build a FinTech startup on a limited budget, resist the urge to build everything. A FinTech MVP does one job well enough that a real customer will use it with real money. Pick the single flow that proves your idea, such as sending a payment, opening an account, or applying for a loan, and cut the rest.
Build the technical foundation
The technical foundation matters more in finance than in most software. Aim for these basics from day one:
-
An API-first, modular architecture, so you can swap technology providers, such as a KYC vendor or a payment processor, without a rewrite.
-
Encryption for data in transit and at rest, plus two-factor authentication for users.
-
A ledger you can reconcile daily. Treat it as a core system. Synapse showed what happens when nobody can.
-
Solid user management: roles, permissions, and audit logs for staff and customers.
-
Solid user management: roles, permissions, and audit logs for staff and customers.
-
Security testing at each release, and a penetration test before launch, ideally by a team with FinTech penetration testing experience.
Whether your FinTech app is a mobile app, a web platform, or an API product, keep your tech stack boring and proven. A proven stack is easier to audit and easier to hire for. The same logic applies when you choose a cloud services provider, where audit evidence and data-residency rules matter as much as price.
Cover the key roles
On the team side, you need three roles covered: a product owner with a deep understanding of the financial domain, app developers who have shipped payment or banking features before, and someone who owns compliance. A small company can cover compliance with a part-time specialist at first.
Choose how to build
You can build in three ways: hire in-house, outsource software development to a partner, or mix both with a dedicated team. In-house gives you control but takes months to recruit, which is why some founders hire FinTech developers through a partner. A dedicated development team model starts faster and lets you add specialists as the product grows.
Learn how we built macro-investing app with its own token and reward system
How Do You Win Your First Customers?
A go-to-market strategy for a FinTech startup starts with your target audience. Pick channels after that. Decide who your first 100 users are, where they already spend time, and what would make them trust a new financial brand. Partnerships often beat ads at this stage: an accounting tool, a community, or a payroll provider can put you in front of potential customers who already trust the channel.
Performance marketing can work once you know your numbers, but customer acquisition in finance is costly, so test small. Referral programs and in-app incentives help you grow your customer base from existing customers at lower cost. Track customer acquisition cost against lifetime value from week one, map the funnel with the AARRR framework, and keep the market in view: a launch that slips by a quarter lets a competitor take the same audience.
How Do You Fund a FinTech Startup and Make Money?
Pre-MVP funding usually comes from your own savings, angel investors, or grants. After you have a working product and early traction, potential investors such as venture capitalists and strategic investors come into the picture. Plenty of founders mix several routes, and some bootstrap for as long as they can to keep ownership.
What investors want now
Investors are selective right now. KPMG's data shows capital concentrating in fewer, larger rounds, so a seed-stage FinTech startup needs a sharper story than three years ago: a clear niche, early per-customer margins, visible growth potential, and a credible plan for compliance. A pitch that says "we will figure out licensing later" does not get far.
How a FinTech business earns money
On the revenue side, a FinTech business earns money in a handful of ways. Transaction fees come first for most payment products: a small percentage or flat fee on each payment, with thin margins until volume grows. Card issuers also earn interchange, a share of the fee merchants pay on every purchase.
Lenders live on the spread between what money costs them and what they charge borrowers. Personal finance and business tools often sell subscriptions for premium features, and infrastructure companies charge other businesses software and API fees.
Most successful FinTech businesses combine two or three of these revenue streams. Choose the business model your first customers will accept, and add others once usage is steady.
Why Do FinTech Startups Fail?
Quoted failure rates vary widely because studies define failure differently. We would rather describe the causes you can control. In our experience, three come up again and again.
Distribution
A working product is only half the battle, and it does not guarantee a business's success. Many startups spend their whole budget on development and nothing on reaching customers. Financial products also carry a trust barrier: people hesitate before handing money to an unknown brand.
Unit economics
If it costs you more to acquire and serve a customer than the customer pays you over time, growth makes things worse. Run the numbers on a spreadsheet before you scale paid marketing.
Compliance treated as an afterthought
Teams that bolt compliance on after launch face a rebuild, a frozen partnership, or a regulator's attention. Teams that build it into the first sprint ship slower at the start and faster afterward.
The dark sides of FinTech
People also ask about the dark sides of FinTech. The real ones are fraud, data breaches, and customers who lose access to their money when a partner fails. A responsible FinTech startup founder designs for those risks before launch.

Our Experience Building FinTech Products
Our FinTech software development team works with startups and established companies, and two lessons stand out.
Bamboo: a micro-investing app
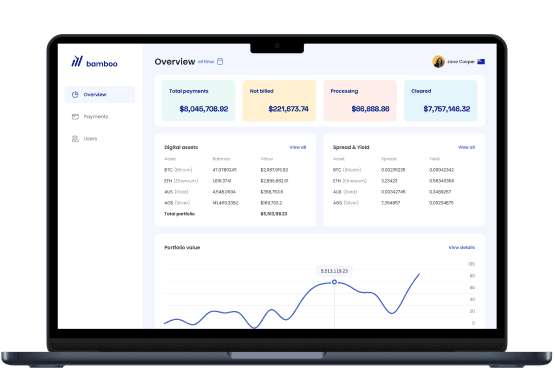
Bamboo is a micro-investing FinTech app where we worked with the team on new features. After the release, active users grew by 700%, and the app now serves more than 20,000 users.
For founders, the lesson is that a small team grows fast when each release targets one clear user behavior. Read the full Bamboo case study.
What we have learned
FinTech startup founders who ask for help early tend to save money. The most expensive conversations we have are with teams who built first and asked about licensing, partners, and security later. A short discovery phase that settles the operating model, the compliance scope, and the MVP boundary costs a few weeks and can save months.
a BPM app using JavaScript stack and Serverless on AWS
Final Thoughts
To start a FinTech company, you need a narrow problem worth solving, a legal route to operate, and a product small enough to ship, in that order. Code comes after the first two. If you want to successfully launch in the FinTech space, treat compliance and partnerships as product work.
Where is this heading?
AI is the biggest shift in the FinTech industry right now, pushing an already rapidly evolving industry to move faster. In H1 2026, AI-related deals drew $21.4 billion across 800 transactions, close to the $23.6 billion invested in all of 2025, per KPMG.
For a new FinTech startup, that means investors will ask how you use AI for fraud detection, underwriting, or support. It also means the bar for a differentiated product keeps rising across the FinTech trends we track.

FAQ
Expect anywhere from about $100,000 for a narrow MVP built on a partner's licenses to several million dollars for a regulated product with its own compliance team. Licensing route, compliance, and scope decide where you land.
Mainly through transaction fees, interchange on card spending, interest and lending spreads, subscriptions, and fees for software or API access. Many FinTech businesses combine two or three of these.
An MVP on a BaaS platform can reach early users in a few months. Your own license can add 12 to 24 months, for example for an e-money institution license in the EU.
No. AI is changing how FinTech products detect fraud, score credit, and serve customers, but companies still need licenses, partners, and trust. Founders who use AI well tend to gain an edge.
Investment is rising, with $103.1 billion in H1 2026, but it is concentrated in large deals. A focused FinTech startup with clear per-customer margins and a compliant model still has room, though the field is not easy.
You can join an existing FinTech as an engineer, product manager, or compliance specialist, or start your own with a validated idea and a licensed partner. Building something small with real users is the fastest way to learn.